Every month, your payslip shows a neat little line called “pension deduction.” You see it, you sigh, and you move on with your life.
Years later, you check your pension account and find gaps. Some months are missing. The money left your salary, but it never arrived in your account.
This happens to more Nigerian workers than you’d think. So let’s talk about what the law says should happen to your pension money, and what you can do when it doesn’t.
First, What Is a Pension Contribution?
A pension contribution is money set aside for your life after work. The law behind it is the Pension Reform Act 2014, and it works like a joint savings plan between you and your employer.
You put in a share. Your employer puts in its own share. Both amounts go into your personal pension account, called a Retirement Savings Account (RSA).
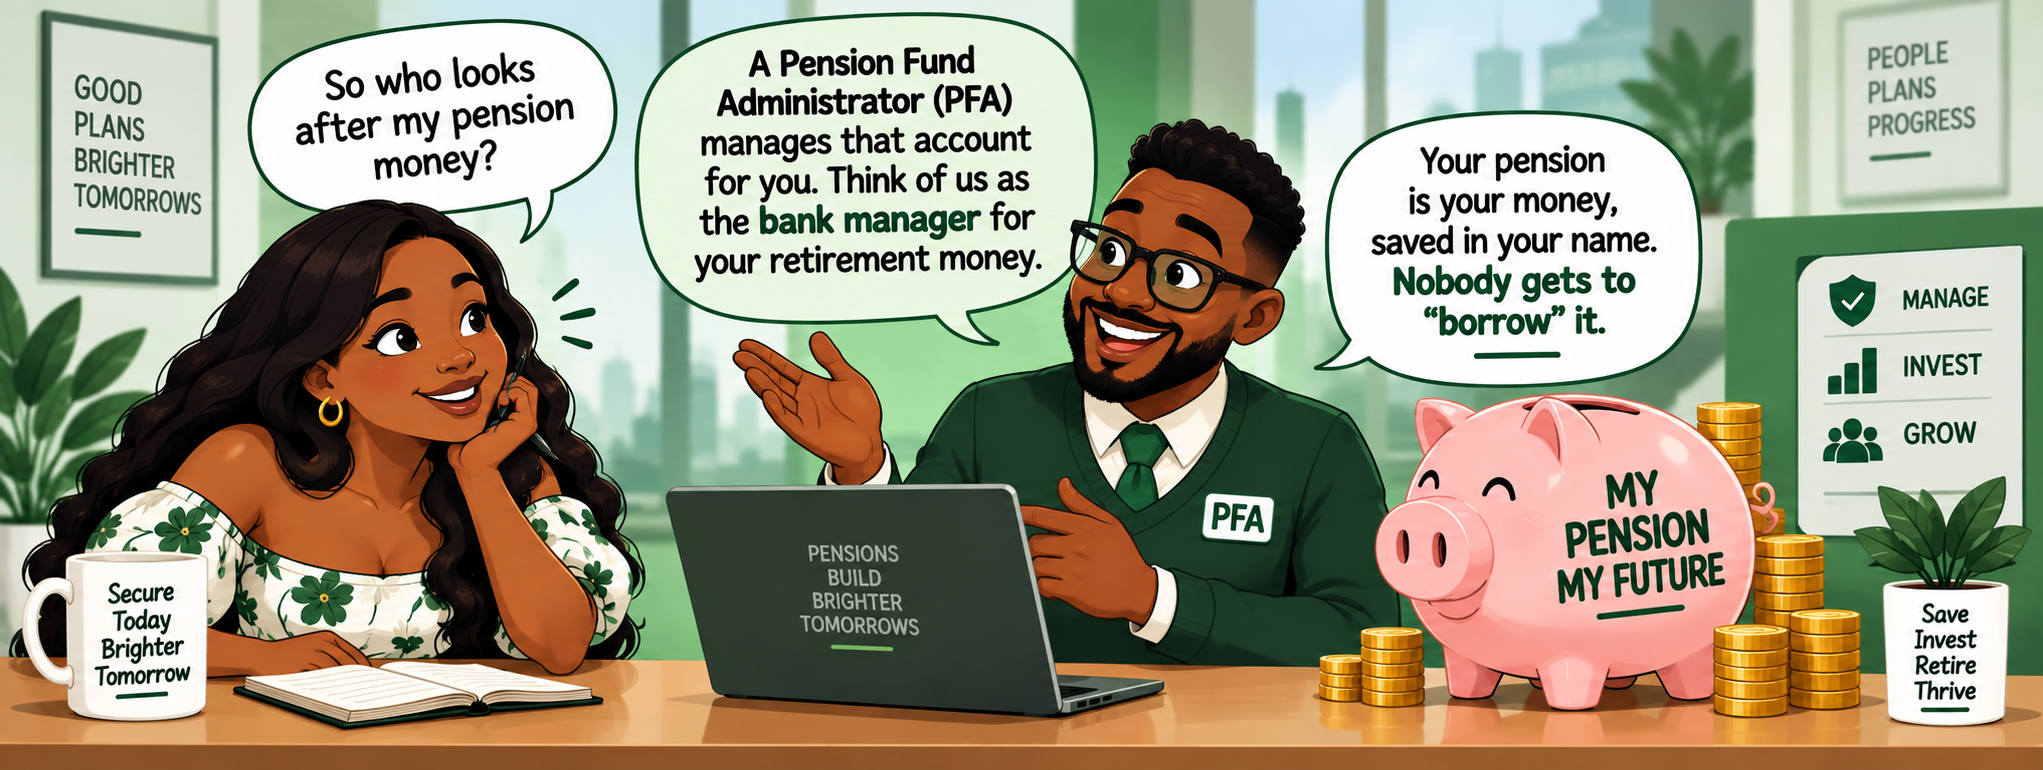
A Pension Fund Administrator (PFA) manages that account for you. The PFA is the bank manager for your retirement money. Your pension is your money, saved in your name. Nobody gets to “borrow” it.
How Much Should Go In Every Month?
The minimum is 18% of your monthly pay. Your employer pays 10%, and you pay 8%. Now, here’s the part many people miss. “Monthly pay” here isn’t just your basic salary. The law says it must include at least your basic salary, housing allowance and transport allowance.
Let’s say Amaka earns ₦150,000 a month: ₦90,000 basic, ₦40,000 housing and ₦20,000 transport.
Her 8% is ₦12,000, deducted from her pay. Her employer adds ₦15,000 of its own money. That’s ₦27,000 going into her RSA every month.
Let me be crystal clear: your employer cannot take the whole ₦27,000 from your salary. Its 10% comes from the company’s pocket, not yours.
And if your employer calculates pension on basic salary alone? Amaka’s monthly total drops to ₦16,200. Her RSA quietly misses out on ₦10,800 every month, or ₦129,600 a year. That falls short of what the law requires.
Check your payslip. Is 8% being calculated on basic, housing and transport combined?
The Seven-Day Rule!
Deducting pension from your salary is only step one. Your employer must then send the money. Both your 8% and the employer’s 10% must be remitted (that’s the legal word for “sent”) within seven working days after salaries are paid. PenCom, the government body that oversees pensions, repeated this deadline in a May 2025 notice.
Money sitting in the company’s bank account doesn’t count. Neither does saving up three months and sending it all at once. That’s a late payment, and the law treats it seriously.
How seriously? Under section 11(7) of the Act, a late employer pays a penalty of at least 2% of the unpaid amount for every month, or part of a month, it stays overdue. And it still owes the original contributions.
PenCom has also appointed recovery agents to go after employers who haven’t paid, with court action on the table.
“But My Company Is Small…”
Now, I know what you’re thinking. Does this even apply to a small business? Honestly, the answer is a little messy.
PenCom’s guidance says the scheme covers private businesses with three or more workers. But section 2(2) of the Act itself says fifteen or more.
So if you work somewhere with three to fourteen staff, don’t assume you’re excluded. Ask HR, or contact PenCom directly. If your employer is already deducting pension from your pay, that money belongs in your RSA, full stop.
Self-employed? You can save voluntarily through the Personal Pension Plan. Unfortunately, there’s no employer top-up there, so every naira comes from you.
The Bonus Protection You Didn’t Know About.
Covered employers must also keep group life insurance for their staff. If a worker dies while employed, this policy pays out to the people they leave behind. Under section 4(5), the cover must be at least three times your total yearly pay, allowances included.
For Amaka, that’s ₦150,000 × 12 × 3 = ₦5.4 million.
It’s worth asking HR whether this policy exists and is current. Your pension doesn’t replace it. Your employer owes you two things here, pension contributions and life cover.
How to Check Your Pension Is Actually Arriving!
Your payslip only proves money was taken. It doesn’t prove the money arrived. Here’s a simple habit. Request your RSA statement from your PFA, then place it next to your last three payslips.
Ask yourself three questions. Does every month show a payment? Does each amount match 18% of your basic, housing and transport? Are your name and pension number correct?
Wrong details can stop money from landing in the right account, even when your employer paid on time.
Emeka spots that March and April are missing from his statement. He emails the accounts team and his PFA, attaching both payslips. Now there’s a paper trail.
If that goes nowhere, PenCom is the regulator you can escalate to. Check your statement at least every quarter. Missing months are easier to chase early.
Why This Matters to You.
Retirement feels far away when rent, fuel and school fees are shouting at you today. I get it. But every missing ₦27,000 is money that should be growing for your future self. Leave it unchecked for five years and you could be looking at over ₦1.6 million, before any investment returns, that never reached your account.
You earned that money. The law protects it. All you need to do is keep an eye on it. So check your RSA statement this week. Then share this post with a colleague, a sibling or that friend who never reads their payslip. The more of us who know the rules, the harder they are to ignore.
It’s your money. Make sure it gets home safely.
For more on handling staff records, read our guide to data protection and employer responsibilities.
Talk to Startpal
If you have questions about pension contributions or would like a consultation, someone on the Startpal team will be happy to talk things through. Get in touch with Startpal or email support@mystartpal.com.
2 Responses