Your loan could get cheaper, but your savings could earn less. An interest-rate announcement can feel like distant Abuja news until your bank tells you it is changing the rates on your money. That is what makes Stanbic IBTC’s latest notice worth reading.
What does the CBN MPR reset mean?
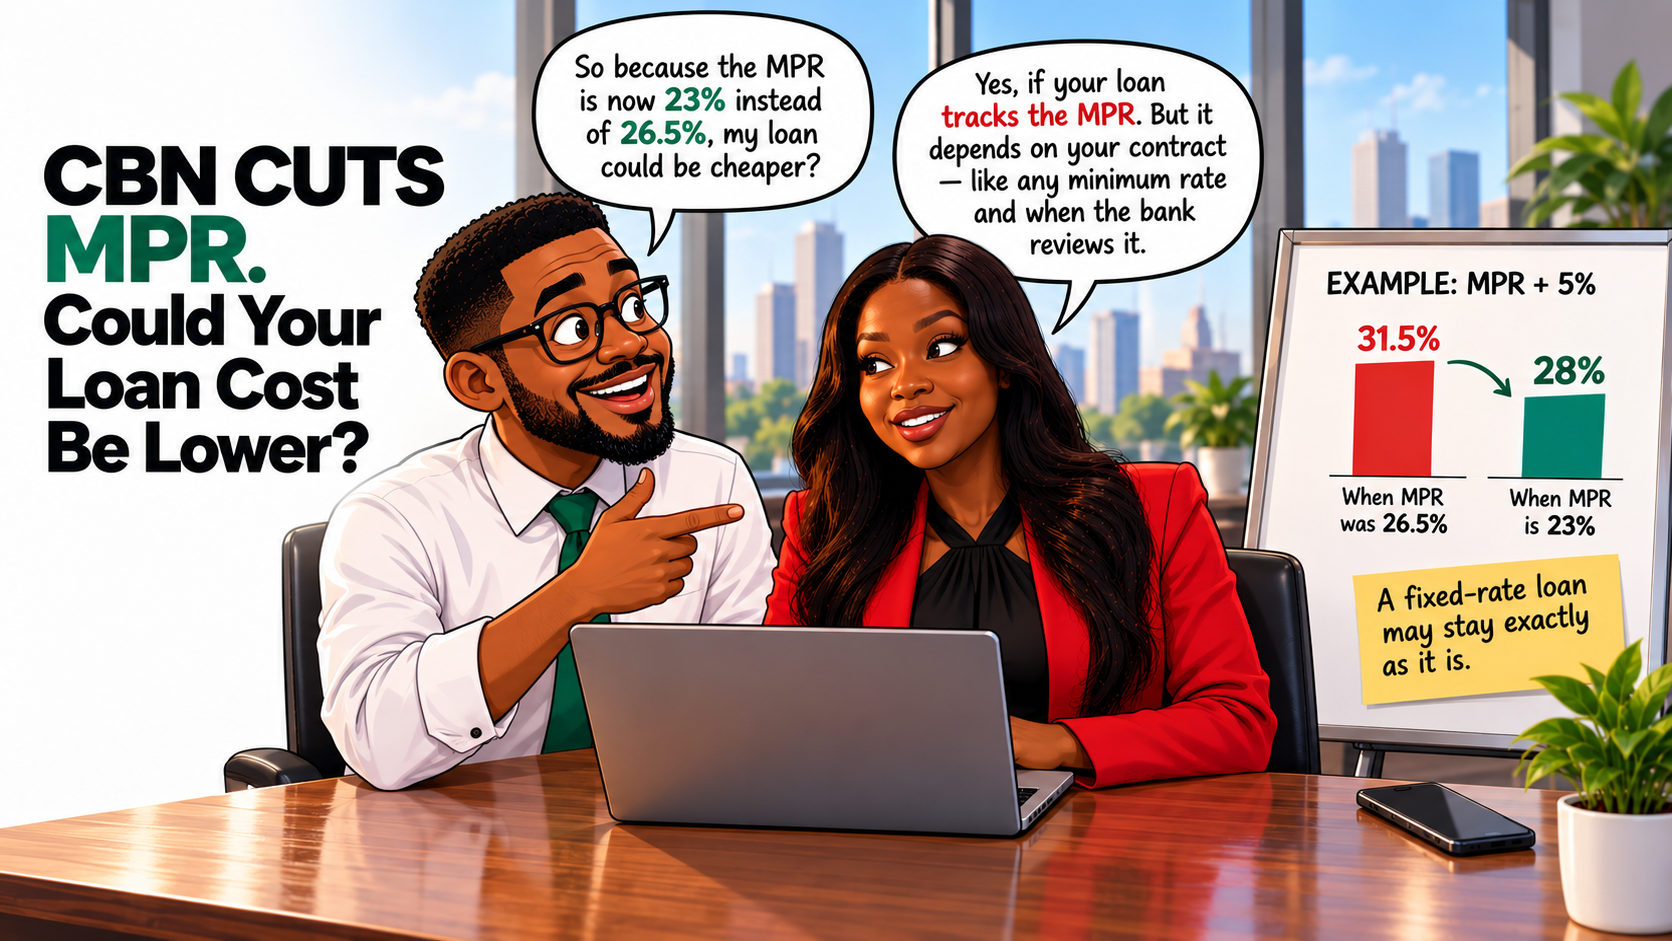
The CBN MPR reset brings the Monetary Policy Rate to 23%, down from 26.5%. The committee made that decision at its meeting on September 21 and 22, 2026. The drop is 3.5 percentage points, also called 350 basis points.
The MPR is a benchmark that helps guide interest rates in Nigeria. It does not automatically become the rate on your loan or savings account. Your bank still has to apply the terms of your particular product.
The committee also adjusted its lending and deposit corridor to +50/-300 basis points around the MPR. It kept reserve requirements at 45% for deposit money banks, 16% for merchant banks and 75% for non-TSA public-sector deposits. These figures govern banks’ dealings with the CBN, rather than the rate printed on your statement.
The CBN described the change as an operational reset to improve how its policy reaches the market. That gives customers a reason to check their rates, but it does not promise cheap loans for everyone.
What did Stanbic tell its customers?
In a customer email dated September 30, Stanbic IBTC said it would lower rates on its MPR-linked products, including loans and deposits. The notice gives September 22, 2026 as the effective date.
That distinction matters because the CBN changed the benchmark, while Stanbic explained how it would apply the change. Stanbic’s notice does not set the rates or start dates for customers at other banks.
Could your loan become cheaper?
If your loan tracks the MPR, the lower benchmark could reduce your interest cost. The result depends on your contract, including any minimum rate and when the bank reviews it. A fixed-rate loan may stay exactly as it is.
For example, suppose a loan charges MPR plus five percentage points, with no minimum rate. Its annual rate would move from 31.5% to 28% once the new benchmark applies. That is an illustration, rather than a quote for any particular Stanbic product.
Your monthly repayment may not fall by the same percentage as the rate. Ask the bank for a revised schedule so the actual figures are clear before changing your budget.
What happens to your savings?
The CBN MPR reset could also reduce the interest on an affected deposit. That is the less exciting side of the announcement if your savings help cover everyday bills.
Check the terms before assuming every account will earn less. An existing fixed-term deposit may keep its agreed rate until maturity, depending on the contract. Ask whether the change affects money already deposited, new deposits, or both.
What should your business check?
Your overdraft or working-capital loan could cost less, while an affected deposit could earn less. Confirm both rates before updating your cash-flow forecast, especially if your business relies on interest income.
Keep the notice and compare it with your contract and bank statement. Finance and compliance teams should check the interest calculation before changing forecasts or explaining the changes to customers.
Ask your bank for the actual numbers
A useful question is: “Is my product linked to the MPR, what is my new rate, and from what date will it apply?”
Request the repayment schedule or deposit-rate confirmation in writing. For an affected Stanbic product, check how the September 22 effective date appears on your statement. If the calculation is unclear, ask the bank to explain it.
The announcement matters when it changes what leaves your account or what your savings earn. Share this with someone who has a loan or deposit, and read more updates in our Regulatory News section.
Have questions or need a consultation? Someone at Startpal is happy to talk through your business and compliance concerns. Contact Startpal to arrange a conversation. Your bank should confirm the specific rate and terms on your account.