Emeka and his four cousins run a logistics company in Apapa. Business is good, and at the end of the year, they have a decision to make about the company profits: share some with the cousins as dividends, or keep the money in the business.
Emeka assumes that if they don’t pay themselves dividends, there’ll be no dividend income to tax.
But under the Nigeria Tax Act, 2025, it isn’t always that simple.
The Act covers two situations worth understanding: when a company pays dividends bigger than its total profits, and when a small group of owners leaves profits in the company that could have been shared.
Here’s how both rules could affect Emeka and his cousins, and your business.
The Company Reports ₦2 Million but Shares ₦10 Million
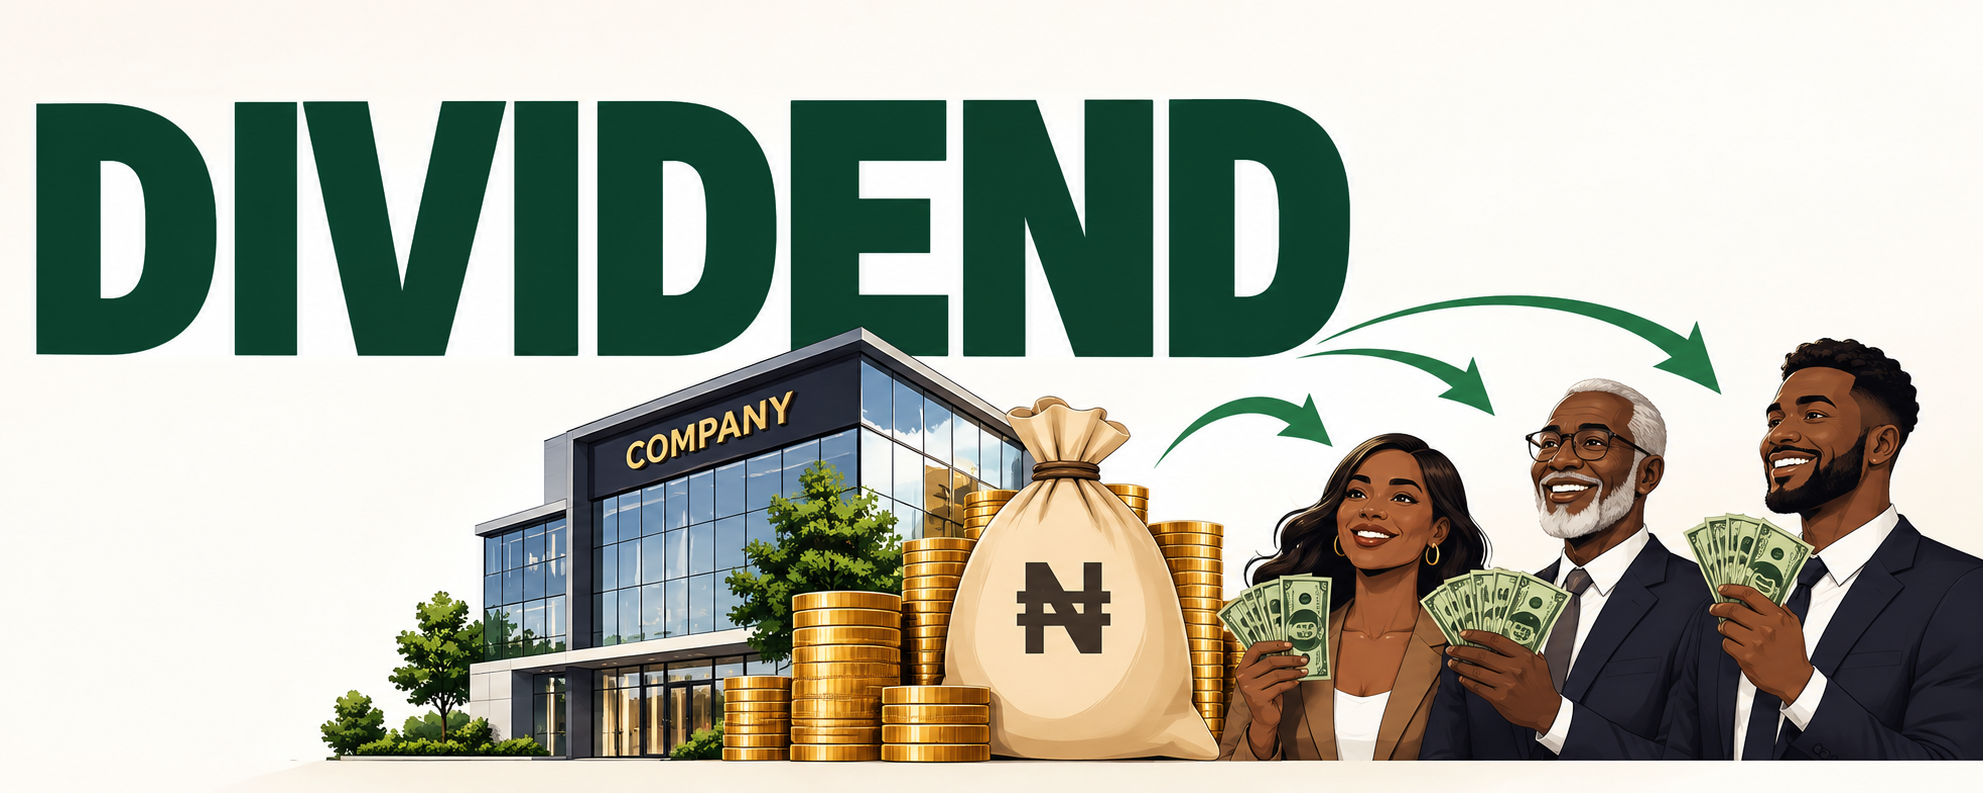
A dividend is money a company pays its shareholders out of its profits.
Suppose Emeka’s company reports total profits of ₦2 million for the year but declares ₦10 million in dividends.
That raises a question: where did the extra money come from?
Under Section 9, if a Nigerian company declares dividends greater than its total profits, or declares dividends when it has no total profits, the dividend may be treated as its total profits for that year.
In Emeka’s case, that means ₦10 million becomes the figure on which the company is taxed, using the applicable rate under Section 56. The tax under this rule falls on the company, whoever receives the dividends.
But before you worry about sharing money saved from previous years, there are exceptions.
What If the Money Came From Earlier Profits?
Emeka’s accountant explains that the company had a strong year in 2023. It paid tax on those profits and saved some of the money. The ₦10 million dividend is coming from those savings.
That changes things.
Section 9 excludes dividends paid from retained earnings that have already been taxed. Retained earnings simply means profits the company kept instead of sharing.
So, if the company paid tax on those profits in 2023 and distributes them in 2026, this rule does not tax those same profits again.
Other exceptions include dividends paid from:
-
Profits exempt from tax under the Act.
-
Franked investment income, generally dividend income that has already been subject to withholding tax.
-
Certain rental and dividend income distributed by real estate investment companies on behalf of their shareholders, whether earned in the current year or earlier years.
The practical point is simple: where the dividend comes from matters. A dividend bigger than this year’s total profits does not automatically create another tax bill under Section 9.
What If Company Profits Stay in the Business?
The next year, the cousins decide to keep all the profits in the company.
There may be good reasons for that. They might need two new trucks, more warehouse space or enough cash to pay drivers and repair vehicles during a slow month.
But suppose the business has more than enough money for its needs, and the owners keep the surplus there to avoid the tax that paying dividends would attract.
That is where Section 10 comes in.
For a Nigerian company controlled by five or fewer individuals, the Nigeria Revenue Service (NRS) may direct that some undistributed company profits be treated as though they had been paid to shareholders.
The key condition is that the company could have shared those profits without harming its business. Keeping money for business needs is relevant to that assessment.
How That Could Affect Emeka
Suppose the company could distribute ₦15 million without affecting its operations, but the cousins decide to keep it all.
Emeka and his four cousins each own 20% of the ordinary shares. If the NRS directs that the ₦15 million be treated as distributed, each person is treated as receiving ₦3 million in dividend income.
They can therefore face tax on that income even though no dividend payment reached their bank accounts.
This is called a deemed distribution: the profits are treated as paid out for tax purposes.
For limited liability partnerships, the Act provides that all profits are treated as distributed, with each partner taxed on their share.
The NRS Has Rules to Follow Too
The NRS cannot simply tell the cousins they owe tax without following the required process.
It must issue a written direction and serve it on the company. That direction must show:
-
The date the profits are treated as distributed.
-
The gross amount treated as distributed.
-
The tax deduction rate applied under the Nigeria Tax Administration Act.
-
The amount remaining after the deduction.
The NRS can also ask for shareholder details by a specified deadline if it reasonably believes that five or fewer individuals control the company.
There is a three-year time limit. A direction must be made within three years of the NRS receiving the audited accounts for the accounting period concerned.
If it receives the company’s audited 2025 accounts in June 2026, that three-year period ends in June 2029. The clock starts when the NRS receives the accounts.
The company can appeal. If it disagrees with the direction, it can challenge it under Chapter Four of the Nigeria Tax Administration Act.
What This Means for Your Company Profits
For Emeka and his cousins, the decision involves more than choosing whether to pay a dividend.
If they share profits, they need records showing where the money came from, including whether it has already been taxed or is exempt.
If they keep profits, they should be able to explain the business reasons. Plans to buy trucks, expand the warehouse or cover running costs help explain why the company needs the money.
The same questions matter if you own a business with relatives or friends:
Where did the dividend money come from? Why is the company keeping its profits? What records support those decisions?
Understanding those points can help you plan and respond if the NRS raises questions.
For more background, read our guides to the Nigeria Tax Act, 2025, tax obligations for Nigerian residents, and dividends and foreign earnings.
Need help working out how these rules apply to your company? Book a consultation with our team to discuss your dividend plans, retained profits and next steps.
Schedule a consultation →