Your friend Tolu runs a small design consultancy in Lekki. Business is booming, and most of her clients are now in Accra, Dubai, and London. Every Nigerian dividend she earns from her company, and every foreign profit it books, sits inside the Nigeria Tax Act 2025.
They pay her in dollars and cedis, straight into an account outside Nigeria. One evening, she suggests that since the money never touched Nigeria, Nigeria cannot tax it.
Under the Nigeria Tax Act, 2025, Tolu is about to learn that this is not the case. The same law also governs every Nigerian dividend, taxing it at its full declared value. Here’s why, and what it means for you.
Your Company Carries Its Tax Passport Everywhere.
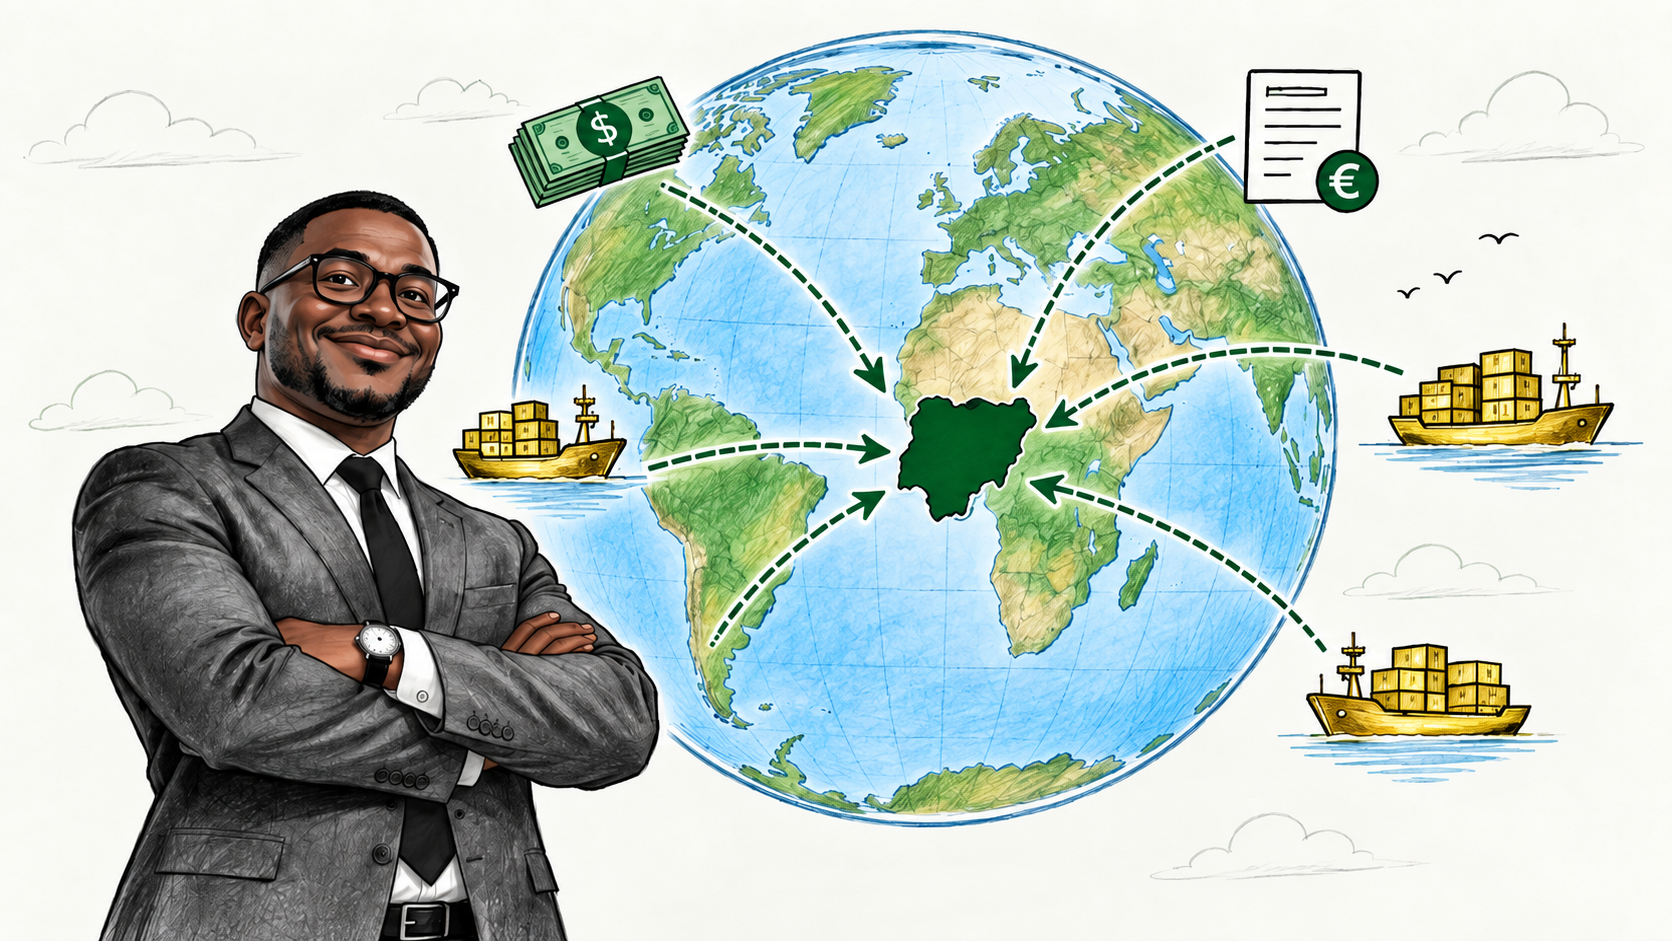
Section 6 of the Act sets out a simple rule. If your company is Nigerian, its profits are treated as earned in Nigeria, no matter where in the world they actually came from.
It also doesn’t matter whether you ever bring the money home. Leaving it in a London account changes nothing.
The tax office call this a worldwide basis of taxation.
For example, Tolu’s company earns ₦50,000,000 in fees from foreign clients this year and keeps every kobo abroad. That ₦50,000,000 still counts as her company’s profit in Nigeria.
Why does the law do this? Your company enjoys Nigeria’s legal protection, its registration system and its corporate identity. The idea is that if Nigeria gives your business a home, your business reports its profits to that home.
The “Let Me Just Park It Offshore” Trick No Longer Works
Now, I know what you’re thinking. “Fine. I’ll open a company in another country, let it earn the money, and simply never pay it out to my Nigerian company.”
Clever. The Act saw you coming.
If a Nigerian company controls a foreign company, and that foreign company refuses to share its profits in a year, the law looks at what could reasonably have been paid out without hurting the business. The Nigerian parent’s share of that amount is then treated as if it had actually been paid, and it gets added to the parent’s profits.
For example: Tolu sets up “Tolu Designs UK Ltd,” which she fully controls. It could comfortably pay out ₦20,000,000 but pays nothing. The law treats that ₦20,000,000 as if it landed in her Nigerian company.
There’s a second safety net. Some countries charge very little tax. If a foreign subsidiary, or another member of the same multinational group, pays tax below the minimum effective tax rate set by the Act, the Nigerian parent must top up the difference.
This is like the tax version of a school’s minimum pass mark. If your child abroad scores below it, the parent at home pays for extra lessons.
The Act asks the Nigeria Revenue Service to issue detailed guidelines on how they work in practice. Therefore, hiding profits in a foreign company, or in a low tax country, won’t delay your Nigerian tax bill.
What Exactly Counts as a “Nigerian Dividend”?
From companies to shareholders now. A dividend is simply your share of a company’s profits, paid because you own part of that company.
Section 7 defines a Nigerian dividend as any dividend paid out by a Nigerian company, and it is measured at the gross amount, which means the full amount declared before anything is deducted.
A company declares a ₦1,000,000 dividend for you. After deductions, ₦900,000 reaches your account. For tax purposes, your dividend is ₦1,000,000, the full declared figure.
Arguing that you never saw the full ₦1,000,000 won’t help.
The definition also covers profits that the law treats as paid out, even if they weren’t. So those “parked” profits we just discussed count the same way as real ones.
When does the dividend count as income? On the day payment becomes due. The day the money actually hits your account doesn’t change that.
So if your dividend becomes due on 31 March and the bank delays it until 10 April, 31 March is the date that matters.
This saves everyone from endless “network issues” arguments. Dividends are counted at their full declared value, from the date they fall due.
How Companies Record the Nigerian Dividends They Receive
Section 8 applies when a company receives dividends from another company. The rule is the same spirit of honesty: include the dividend in your profits gross, before any tax already deducted at source.
Now for some good news. If a company pays its dividend in shares instead of cash, the receiving Nigerian company does not include it in its taxable profits. Those share dividends are also free from the deduction under section 50 of the Nigeria Tax Administration Act.
For example: Instead of cash, a company gives Tolu’s business 10,000 extra shares as its dividend. No cash has arrived, so there’s nothing to tax yet.
Why is this fair? Extra shares are a paper benefit. You can’t pay salaries or buy diesel with them until you sell. Taxing them would force a business to find real cash for money it hasn’t actually received.
Takeaway: Cash dividends are taxed at their full value; dividends paid as shares are left alone.
Why This Matters to You
Maybe you have clients abroad, own shares, or have a boss who keeps saying “offshore structure” in meetings.
Either way, these rules shape real decisions. They tell you that distance won’t hide profits, that dividends are counted honestly, and that common sense applies where no real money has changed hands.
Knowing this early can save you penalties and some very awkward conversations with the tax office. For more on how the Act treats residents earning abroad, see our companion post on tax obligations in Nigeria. If you’re new to the Act, start with our explainer on the Nigeria Tax Act 2025.
If this cleared things up, share it with that friend who thinks foreign accounts are invisible. The more of us understand these rules, the better we can plan, ask the right questions, and hold our own when it counts.
Feeling overwhelmed?
We know the terminology can feel dense, and it’s easy to read something like this and still not be sure where your own situation lands. If you’d like to talk it through, someone on our team would be genuinely happy to sit with you. Book a consultation and we’ll go through your specific circumstances, what applies to you, and what your next step looks like.
Schedule a consultation →