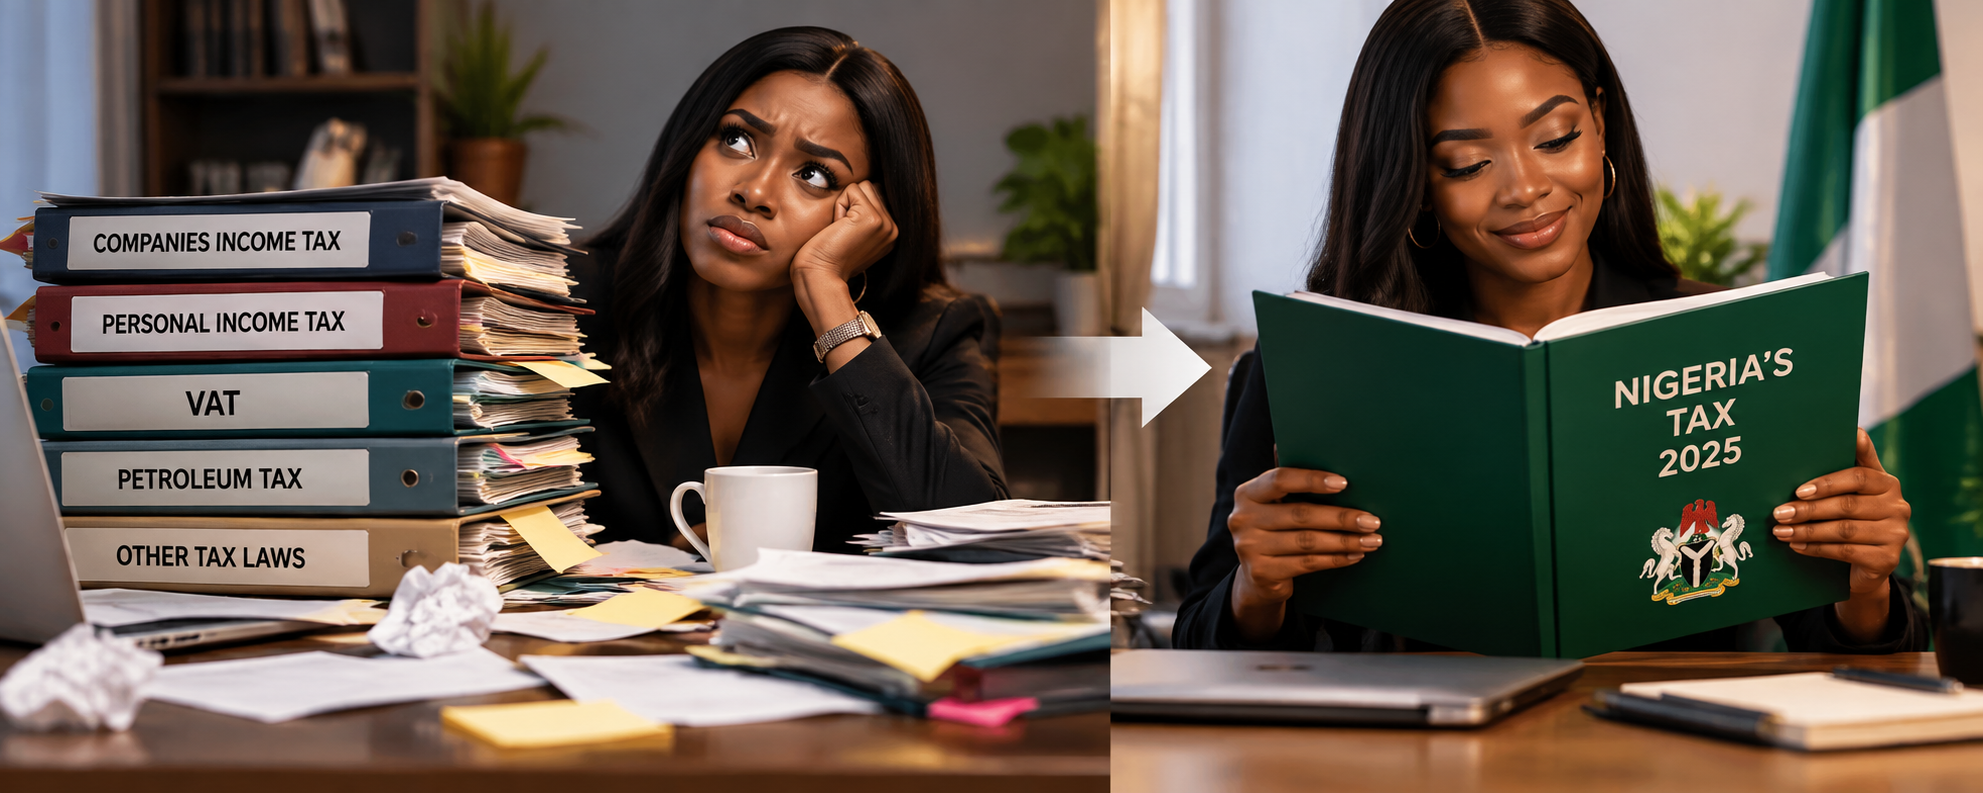
Nigeria used to have tax rules scattered across several different laws, like a recipe split across five cookbooks that disagreed with each other. The Nigeria Tax Act 2025 gathers all of it into one book. It says plainly what tax is for, who it applies to, what counts as income, and who is on the hook to pay.
How Did This Happen?
Before this, understanding your tax meant hopping between old laws written in different decades, each with its own language and its own quiet contradictions. If two of them clashed, good luck. Most people gave up and paid a consultant to explain something that should have been obvious.
So the Act opens by stating its purpose: one unified fiscal law for taxation in Nigeria. Fewer places to look, fewer arguments about which rule wins.
What Does the Nigeria Tax Act 2025 Cover?
The Act applies across Nigeria to anyone required to comply with tax law. Here is the part people miss: it covers you whether you’re acting for yourself or for somebody else. Accountants, agents, guardians and company officers stand in the same net as their clients. No hiding behind “I was just the middleman.”
Who the Nigeria Tax Act 2025 Taxes
The Act taxes three groups: companies and enterprises, individuals and families, and trustees or estates. Families matter here because Nigerian property often sits in collective hands. Where family income is genuine and nobody’s share can be separated, the law treats the pool as one. The Act also spares inherited assets until an executor actually distributes them. That means the tax authority does not touch property still sitting in dispute.
What Counts as Income
Section 4 is the big one, the list of what counts as income. Profits from any trade, business or profession. Royalties, rents, interest, dividends, premiums, annuities, fees and allowances. Discounts and rebates. Profits from selling property or fixed assets. Prizes, winnings, honoraria, grants and awards, so your lucky raffle win counts as seriously as your salary. The Act names digital assets outright. That means the person flipping crypto on their phone sits in exactly the same frame as the landlord collecting rent.
For employees: salaries, wages, bonuses, benefits, perquisites, pensions. The Act excludes genuine expense reimbursements. So getting your fuel money back for a work trip does not count as income.
How the Bill Follows You
Then there’s the naming part, which sounds boring but decides who actually pays. The Act lets the tax authority charge the company in its own name. It can also charge through a principal officer, attorney, agent or representative in Nigeria. The bill stays the same either way. If the company collapses, a receiver, liquidator or administrator steps in. The tax authority can charge them in their name too, at exactly the same amount as if nothing had happened. Insolvency is not an exit door. Individuals follow the same logic through families, trustees, estates or agents. The intermediary changes; the bill doesn’t.
Why Is Everyone Worried?
Because the net is wider than most people realised, and the excuses have grown thinner. Crypto traders who assumed they were invisible now have a line of statute with their name on it. Families holding property jointly may receive a tax bill covering the whole pool rather than a single person. And agents who thought “I only signed on behalf of my client” was a defence will discover the Act closed that door on page one.
The upside is real though. One law means you can actually read it and know where you stand. No more paying somebody to translate three conflicting statutes into a guess.